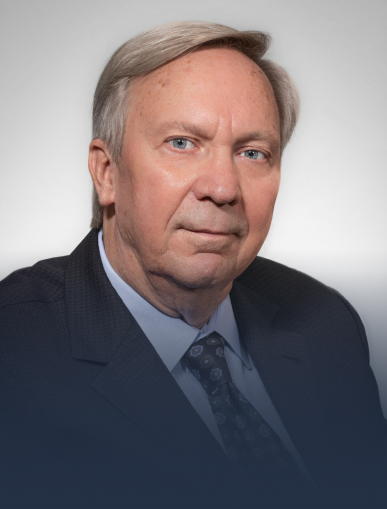
Our firm is investigating Bankers Life Securities, Inc. and Bankers Life Advisory Services financial advisor and broker Myles William Easter (CRD#6024704) of West Des Moines, Iowa for potential investment-related misconduct involving allegations concerning annuity recommendations, product features, liquidity restrictions, suitability, and misrepresentations. Investors who believe they suffered financial losses because of similar conduct can speak with an experienced investment fraud lawyer about their potential recovery options.
Financial Advisor’s Career History
According to the uploaded FINRA BrokerCheck report, Easter was previously registered with New England Securities in West Des Moines, Iowa from September 2012 through October 2012. He later worked at Bankers Life as a Unit Field Trainer beginning in October 2012, became registered with Bankers Life Securities, Inc. on June 14, 2018, and became registered with Bankers Life Advisory Services, Inc. on January 9, 2024. His current reported office location is 160 South 68th Street, Suite 1205, West Des Moines, Iowa 50266.
Myles William Easter Fraud Allegations and Investor Complaints Explained
FINRA BrokerCheck reflects four customer dispute disclosures for Easter, all listed as final, with no pending customer disputes shown in the report. The disclosed matters center on alleged misrepresentations, annuity exchanges or replacements, liquidity restrictions, and suitability concerns involving Guaranteed Lifetime Income Annuities and equity-indexed annuity transactions.
2019 settled complaint involving alleged GLIA misrepresentation
One written complaint, dated February 27, 2019 and received March 2, 2019, alleged that Easter misrepresented the terms of a Guaranteed Life Income Annuity purchased through Bankers Life and that the product was unsuitable. The complaint further alleged that the client lost a significant amount of income base when a variable annuity was liquidated and that the funds were locked up for 10 years. BrokerCheck lists alleged damages of $17,235, and shows the matter settled on September 10, 2019 for $17,125, with no individual contribution by Easter.
2020 denied complaint seeking $95,000 in restitution
Another written complaint, dated March 24, 2020 and received March 30, 2020, alleged that after two equity-indexed annuities were voided in September 2019, the customer purchased a new annuity elsewhere and claimed the previously surrendered variable annuity had offered more guaranteed income and benefits. The complaint sought restitution of $95,000. BrokerCheck lists this matter as denied on May 7, 2020.
2020 withdrawn complaint over rollover and withdrawal limits
A separate written complaint, dated October 27, 2020 and received November 4, 2020, alleged that Easter recommended rolling over $125,000 of existing investments into a Guaranteed Lifetime Income Annuity in May 2020, that the client felt pressured into the purchase, and that the client was not properly informed that only 10% of invested funds could be accessed penalty-free during the first twelve months. BrokerCheck lists alleged damages of $12,500 and states that the complaint was withdrawn on November 17, 2020 after the client advised she wished to keep the investment.
2021 FINRA arbitration resulting in a customer award
BrokerCheck also shows FINRA arbitration Case No. 21-01192. The claim was served in May 2021 and alleged misrepresentations inducing a client to surrender two annuities sold by another firm in order to purchase two Guaranteed Lifetime Income Annuities issued by a Bankers Life affiliate in December 2018. The customer claimed that although the Bankers Life annuities were later refunded in September 2019, the replacement investments purchased elsewhere lacked prior features and produced less income. BrokerCheck lists alleged damages of $50,000. On January 28, 2022, the matter resulted in an award requiring Easter to pay $30,000 in compensatory damages, $150 as reimbursement of the non-refundable filing fee, and interest; the report lists Easter’s individual contribution amount as $30,000.
For context, the disclosures listed in BrokerCheck include:
- Customer complaint received March 2, 2019 — alleged misrepresentation and unsuitable GLIA recommendation; alleged damages $17,235; settled on September 10, 2019 for $17,125; individual contribution $0.
- Customer complaint received March 30, 2020 — alleged loss of guaranteed income and benefits after annuity changes; demanded $95,000; denied on May 7, 2020.
- Customer complaint received November 4, 2020 — alleged pressure to roll over $125,000 and inadequate disclosure of first-year liquidity limits; alleged damages $12,500; withdrawn on November 17, 2020.
- FINRA arbitration Case No. 21-01192 — alleged misrepresentation tied to surrender of two annuities and purchase of two GLIAs; alleged damages $50,000; award to customer entered January 28, 2022 for $30,000 plus $150 filing-fee reimbursement and interest.
Taken together, the disclosures reported on Easter’s BrokerCheck record may raise questions concerning annuity replacements, unsuitable investment recommendations, liquidity restrictions, and whether material product features were accurately explained before transactions were completed.
Investors who suffered losses after being given allegedly inaccurate or incomplete information about an investment can also review our resources concerning fraud and misrepresentation. Depending on the relationship and underlying facts, claims may also involve negligence and breach of fiduciary duty.
Because several of the reported matters concern annuity products, investors with similar losses can also review our information about variable annuities and equity-indexed annuities.
Can Investors Pursue a FINRA Arbitration Claim?
Investors seeking monetary compensation generally need to pursue their own claim even when a broker has prior customer-dispute disclosures. An experienced FINRA arbitration lawyer can review annuity contracts, surrender documents, account records, financial profiles, communications, disclosures, and damages to determine whether a viable claim exists.
A prior settlement or arbitration award involving another customer does not automatically establish liability in a different investor’s case.
Robert Wayne Pearce Is Committed to Recovering Your Investment Losses
FINRA Rule 2111 – Suitability addresses the suitability obligations applicable to covered investment recommendations. The analysis may consider factors such as the customer’s age, financial circumstances, investment objectives, risk tolerance, liquidity needs, time horizon, and investment experience. In the complaints disclosed on Easter’s BrokerCheck record, the allegations repeatedly concern annuity exchanges, income benefits, extended holding periods, and withdrawal restrictions—the kinds of considerations that can be relevant to a suitability analysis.
FINRA Rule 2010 – Standards of Commercial Honor requires FINRA members to observe high standards of commercial honor and just and equitable principles of trade. If substantiated, allegations that an advisor materially misrepresented annuity terms or failed to accurately explain significant product restrictions may raise issues under Rule 2010 depending on the underlying facts.
FINRA Rule 2010 – Standards of Commercial Honor requires FINRA members to observe high standards of commercial honor and just and equitable principles of trade. If substantiated, allegations that an advisor materially misrepresented annuity terms or failed to accurately explain significant product restrictions may raise issues under Rule 2010 depending on the underlying facts.
Myles Easter Investors in Iowa and Surrounding States
Easter works in West Des Moines, Iowa, and the Law Offices of Robert Wayne Pearce, P.A. represents investors throughout Iowa and the surrounding Midwest.
Investors with similar annuity or brokerage disputes can also review resources from a Missouri investment fraud lawyer, Minnesota investment fraud lawyer, or Nebraska investment fraud lawyer.
The Law Offices of Robert Wayne Pearce, P.A. is a nationally recognized securities law firm representing investors in FINRA arbitration and securities fraud cases on a contingency fee basis. Robert Wayne Pearce, the founding attorney, has more than 45 years of experience recovering millions for victims of broker misconduct and investment fraud. He previously defended major brokerage firms and now uses that insight to protect investors nationwide. To discuss your case directly with Mr. Pearce, call (800) 732-2889 or email pearce@rwpearce.com for a free consultation.
The investment fraud lawyers at the Law Offices of Robert Wayne Pearce, P.A. represent investors nationwide in claims involving unsuitable recommendations, annuity sales, misrepresentations, negligence, fiduciary breaches, supervisory failures, and other securities-related misconduct.