Category: News & Articles

FREE INITIAL CONSULTATION WITH ATTORNEYS WHO CAN HANDLE YOUR SECURITIES, COMMODITIES AND INVESTMENT PROBLEMS

The Law Offices of Robert Wayne Pearce, P.A. understands what is at stake in securities, commodities and investment law matters and constantly strives to secure the most favorable possible result. Mr. Pearce provides a complete review of your case and fully explains your legal options. The firm works to ensure that you have all of the information necessary to make a sound decision before any action is taken in your case.

For dedicated representation by a law firm with substantial experience in all kinds of securities, commodities and investment disputes, contact the firm by phone at 833-300-6983, toll free at 800-732-2889 or via e-mail. We may also be able to arrange a meeting with you at offices located in Boca Raton, Fort Lauderdale, Miami and West Palm Beach, Florida and elsewhere.

Collateralized Loan Obligations (CLOs) – What Investors Need to Know About Hidden Risks, Unsuitable Recommendations, and Their Legal Rights

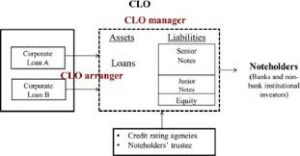
If your broker or financial advisor recommended Collateralized Loan Obligations—commonly called CLOs—and you have suffered significant investment losses, you are not alone. CLOs have become one of the fastest-growing and most aggressively marketed products in the retail investment landscape, with the U.S. CLO market now exceeding $1.13 trillion in outstanding issuance. Unfortunately, the explosive growth of CLO-focused exchange-traded funds (ETFs) and closed-end funds has pulled everyday investors into a corner of finance historically reserved for sophisticated institutions, often with devastating results. At the Law Offices of Robert Wayne Pearce, P.A., we have recovered over $185 million for investors harmed by unsuitable recommendations, broker misconduct, and failure to disclose material risks. Attorney Robert Wayne Pearce has more than 45 years of experience representing investors in FINRA arbitration and securities litigation involving complex structured products, and he is prepared to evaluate your CLO-related losses at no cost.

Keep Reading

Raymond James Financial Services Advisor Mario Payne Under Investigation For Customer Disputes Alleging Unsuitable Structured Products and Misrepresentations

Our firm is investigating former Raymond James Financial Services financial advisor Mario Payne (CRD# 5445757) of Jacksonville, Florida for potential investment-related misconduct. Financial Advisor’s Career History FINRA BrokerCheck reflects that Mario Payne is not currently registered as a broker, but was previously registered with Edward Jones in Jacksonville, Florida from December 2007 to May 2013 and with Raymond James Financial Services, Inc. in Jacksonville, Florida from May 2013 to February 2019. His most recently reported Form U4 employment history lists Planning Solutions International LLC dba TOAMS Financial (Jacksonville, Florida) from February 2019 to present as Owner/Chief Compliance Officer, and also reflects roles at Raymond James Financial Services, Inc. (Financial Advisor) and Raymond James Financial Services Advisors Inc. (Investment Adviser Representative) from May 2013 to February 2019.

Keep Reading

RBC Capital Markets, LLC Financial Advisor Paul Meyer Under Investigation For Alleged Unauthorized Discretionary Trading and Customer Complaints

Our firm is investigating RBC Capital Markets, LLC financial advisor Paul Richard Meyer (CRD# 3062534) of Minnetonka, Minnesota for potential investment-related misconduct. Financial Advisor’s Career History According to his BrokerCheck report, Paul Richard Meyer has been registered with RBC Capital Markets, LLC since October 11, 2017. His reported employment/registration history includes: RBC Capital Markets, LLC — Financial Advisor (10/2017–Present) (Minnetonka, MN) City National Bank (affiliate role) — Employee of an affiliate (06/2018–12/2023) (Minnetonka, MN) Morgan Stanley Private Bank, National Association — Financial Advisor (01/2015–10/2017) (New York, NY) Morgan Stanley Smith Barney — Mass Transfer (06/2009–10/2017) (Minneapolis, MN) Morgan Stanley & Co. Incorporated — Financial Advisor (08/2008–10/2017) (Minneapolis, MN) RBC Capital Markets Corporation — Registered (06/1998–08/2008) and Investment Adviser registration (04/2005–08/2008) (Minneapolis, MN)

Keep Reading

Variable Universal Life Insurance – Risks and Problems and Your Options

What Is Variable Universal Life Insurance? Variable universal life insurance (VUL) is a permanent life insurance policy with a cash value component invested in market-based sub-accounts, sold by broker-dealers, insurance agents, and dual-registered financial advisors as a tax-advantaged alternative to traditional retirement savings vehicles like 401(k)s and IRAs. Each VUL policy has two components: a death benefit and a cash value account. The policyholder pays flexible premiums, and after the insurer deducts charges for mortality, administration, and insurance costs, the remainder flows into sub-accounts that function like mutual funds. These sub-accounts invest in equities, bonds, or money market instruments, and the cash value rises or falls based on market performance. VUL is the only life insurance product classified as a security under federal law, requiring registration with the SEC and delivery of a prospectus. Sellers must hold both a state insurance license and a FINRA securities registration (Series 6 or Series 7). Major issuers include Prudential Financial, Pacific Life, Northwestern Mutual, Lincoln National, and Equitable Financial. LIMRA reported that VUL new annualized premiums reached $2.4 billion in 2024, a 27% year-over-year increase. What Are the Hidden Risks of Variable Universal Life Insurance? VUL policies expose investors to layered risks that are difficult to identify before purchase and impossible to eliminate after. The combination of market risk, rising internal charges, and illiquidity creates a product where losses compound silently over time. Market risk is direct and unprotected. Unlike indexed universal life policies, which offer a floor on returns, VUL sub-accounts carry the full downside of their underlying investments. A 30% market decline reduces cash value by 30%—plus whatever the insurer deducts that month for cost of insurance, mortality and expense charges, and administrative fees. The cost of insurance (COI) charge is the most dangerous hidden cost because it increases every year as the policyholder ages. The Consumer Federation of America found that COI rates in one VUL policy were $1.98 per $1,000 of coverage when comparable term insurance cost $0.55 per $1,000—a 260% markup. As the policyholder ages, these charges accelerate, consuming an ever-larger share of the cash value. This dynamic creates a “death spiral”: market losses reduce cash value, but rising COI charges continue regardless, depleting the account faster. If cash value falls to zero, the policy lapses. The policyholder loses all premiums paid, the death benefit disappears, and any prior distributions may become taxable as ordinary income—even though no cash is received. How Are Variable Universal Life Insurance Fees Hidden from Investors? VUL fees are distributed across multiple layers that are disclosed in the prospectus but rarely itemized in a way that allows investors to calculate the total cost. The annual cost drag on a typical VUL policy ranges from 2–4% or more of invested cash value, compared to 0.03–0.10% for a low-cost index fund. The first deduction occurs before a dollar is invested. Premium loads—sales charges deducted from each premium payment—typically range from 5–9%. On a $50,000 annual premium, $2,500–$4,500 is removed upfront. Mortality and expense (M&E) charges of 0.40–1.75% per year are deducted from the sub-account values. Administrative fees of $5–$15 per month add another $60–$180 annually. Sub-account management fees, equivalent to mutual fund expense ratios, range from 0.50–2.00% per year. Surrender charges create an additional trap. Most VUL policies impose declining surrender charges over a period of 10–15 years, sometimes extending to 20 years. A policyholder who discovers the true cost of the product within the first few years faces a penalty of 5–10% or more of the cash value to exit. This illiquidity distinguishes VUL from a brokerage account or IRA, where an investor can sell holdings at any time without a surrender penalty. Why Do Brokers and Agents Recommend Variable Universal Life Insurance Despite the Risks? Brokers and insurance agents recommend VUL because the product pays first-year commissions of 70–110% or more of the target premium. On a $50,000 annual VUL premium, the selling agent can earn $35,000–$50,000 in the first year alone. By comparison, a term life insurance policy with a $500 annual premium generates a first-year commission of $250–$350, and a low-cost index fund generates no commission at all. This compensation gap creates a conflict of interest that regulators have identified as a persistent problem. The Consumer Federation of America concluded that in VUL sales, “the profit motive overrides all other considerations for insurers and many insurance agents.” A broker who recommends VUL as a retirement savings vehicle earns dramatically more than one who recommends maximizing 401(k) contributions and purchasing a term life policy. FINRA has warned that firms must manage these conflicts under Regulation Best Interest (Reg BI), which requires broker-dealers to act in the retail customer’s best interest. FINRA’s 2024 Annual Regulatory Oversight Report identified “the variable annuity space” as one of two areas generating the most Reg BI compliance problems—a finding that extends to variable life insurance products subject to the same regulatory framework. Is Variable Universal Life Insurance Suitable as a Retirement Savings Vehicle? VUL is unsuitable as a primary retirement savings vehicle for most investors because its internal costs consume returns that would otherwise compound toward retirement goals. An investor who has not yet maximized contributions to a 401(k) ($23,500 annual limit in 2025) and IRA ($7,000 limit) is almost certainly better served by those vehicles before considering VUL. FINRA Notice to Members 00-44 specifically addressed VUL suitability, stating that VUL “may be appropriate for a customer with a need for life insurance AND an ability to pay for permanent life insurance protection.” The notice identified unsuitable sales patterns including sales to “retirees and persons who did not know that they were purchasing insurance or did not want life insurance.” The absence of either a genuine insurance need or the financial capacity to sustain premiums long-term renders VUL unsuitable. The “buy term and invest the difference” comparison exposes the cost disparity. A 30-year-old healthy male can purchase a 20-year, $500,000 term policy for approximately $300–$500 per year. Investing the premium savings in a low-cost S&P 500 index...

Keep Reading

Hornor, Townsend & Kent Financial Advisor Aaron Wagner Under Investigation for Variable Annuity Misrepresentation and FINRA Customer Complaints

Aaron Wagner (CRD# 5663584) is a former financial advisor who was registered with Hornor, Townsend & Kent, LLC and previously associated with AXA Advisors, LLC and Pruco Securities, LLC, with reported office locations including Boise, Idaho and Bellevue, Washington. Financial Advisor’s Career History Aaron Wagner entered the securities industry in or around 2009. According to FINRA records, he was registered with AXA Advisors, LLC from August 2009 through February 2013. He later became registered with Pruco Securities, LLC from February 2013 until October 2014. Wagner then joined Hornor, Townsend & Kent, LLC, where he was registered from March 2015 through July 2020. He is not currently registered with any FINRA member firm.

Keep Reading

D. Boral Capital Stockbroker Brendan Behan Under Investigation For Unsuitable Transactions, Unauthorized Trading, and Churning FINRA Complaint

Our firm is investigating D. Boral Capital stockbroker Brendan Bryan Behan (CRD# 5681974) of Woodbury, New York for potential investment-related misconduct. Stockbroker Career History Brendan Bryan Behan is currently registered with D. Boral Capital in Woodbury, New York, where BrokerCheck shows he has been registered since March 4, 2024. His prior registrations listed in BrokerCheck include Aegis Capital Corp. in Melville, New York from July 2023 through March 2024 as an investment adviser representative, Aegis Capital Corp. in Melville, New York from September 2012 through March 2024 as a broker, Max International Broker/Dealer Corp. in New York, New York from June 2009 through January 2013, and NSM Securities, Inc. in West Palm Beach, Florida from July 2012 through September 2012. Brendan Bryan Behan Fraud Allegations and Investor Complaints Explained FINRA BrokerCheck reflects two final customer dispute disclosures for Mr. Behan, both reported as settled. The reported allegations include unsuitable transactions, unauthorized trading, and churning, with both matters tied to his time at Aegis Capital Corp. BrokerCheck also notes that customer disputes may contain allegations that are contested, unresolved, or settled without any admission or finding of wrongdoing.

Keep Reading

Penny Stocks: What are the Risks and Your Legal Rights after suffering losses?

Penny stocks are equity securities trading below $5 per share, typically on over-the-counter (OTC) markets rather than major exchanges like the NYSE or Nasdaq. The SEC defines them under Securities Exchange Act Rule 3a51-1 and subjects them to heightened disclosure and suitability requirements because of the outsized risks they pose to retail investors. Most penny stocks trade through OTC Markets Group, which oversees more than 12,000 securities across a tiered marketplace. The OTCQX Best Market requires audited financials and excludes penny stocks entirely. The OTCQB Venture Market requires a minimum $0.01 bid price and current reporting. Below these, the Pink Market and Grey Market house securities with limited or no public disclosure—many have no audited financial statements and no obligation to report to the SEC.

Keep Reading

LPL Financial Advisor James Chiaro Under Investigation For Failure to Timely Execute Trades FINRA Complaint

Our firm is investigating LPL Financial broker and investment adviser James Patrick Chiaro (CRD# 4866429) of Dunmore, Pennsylvania for potential investment-related misconduct. James Patrick Chiaro’s Career History James Patrick Chiaro is currently registered with LPL Financial LLC in Dunmore, Pennsylvania, where he has been registered as both a broker and an investment adviser since August 18, 2017. BrokerCheck shows prior registrations with Citizens Securities, Inc. from 2007 to 2017 and PNC Investments from 2005 to 2007. The report also reflects employment history entries including LPL Financial, LLC and CCO Investment Services Corp. James Patrick Chiaro Fra

Keep Reading

NYLIFE Securities Financial Advisor Mark Kissinger Under Investigation For Unsuitable Variable Universal Life Insurance Recommendation FINRA Complaint

Our firm is investigating Frisco, Texas financial advisor and stock broker Mark Perry Kissinger (CRD# 4546631), who is currently registered with NYLIFE Securities LLC and Eagle Strategies LLC out of 2600 Network Blvd., Suite 130, Frisco, Texas, for potential investment-related misconduct. Financial Advisor’s Career History According to FINRA BrokerCheck, Kissinger entered the securities industry in 2002 with A.G. Edwards & Sons, Inc. in McKinney, Texas, where he was registered from August 2002 through August 2007 as a broker and from September 2002 through August 2007 as an investment adviser representative. He was then registered with UBS Financial Services Inc. from August 2007 through November 2011 in Addison and McKinney, Texas, later with Allstate Financial Services, LLC in Frisco, Texas from April 2012 through November 2018, and has been registered with NYLIFE Securities LLC since November 27, 2018 and Eagle Strategies LLC since March 15, 2023. His recent employment history also lists Kissinger Financial Services LLC, New York Life Insurance Company, and Nylife Securities LLC in Frisco, Texas.

Keep Reading

Emerson Equity LLC Broker James Raia Under Investigation For Unsuitable Investment Recommendations and Misrepresentation FINRA Complaint

Our firm is investigating Emerson Equity LLC stockbroker James John Raia (CRD# 2397301) of Irvine, California for potential investment-related misconduct. Stockbroker’s Career History According to FINRA BrokerCheck, James John Raia has been registered in the securities industry since 1996. His current registration is with Emerson Equity LLC, where he has been registered since May 7, 2025. Before joining Emerson Equity LLC, Raia was registered with Moloney Securities Co., Inc. from February 2018 through June 2025, Summit Brokerage Services, Inc. from September 2015 through February 2018, J.P. Turner & Company, L.L.C. from December 2009 through September 2015, GunnAllen Financial, Inc. from February 2005 through December 2009, Greenpoint Securities LLC from January 2004 through December 2004, Essex National Securities, Inc. from October 1997 through January 2004, MetLife Securities Inc. from August 1997 through October 1997, Metropolitan Life Insurance Company from August 1997 through October 1997, Shamrock Financial Services from December 1996 through August 1997, and Continental Broker-Dealer Corp. from March 1997 through July 1997.

Keep Reading
1 … 8 9 10 11 12 … 53