Category: Investor Losses

What Are Credit Default Swaps? Risks for Retail Investors and How to Recover Losses

Credit Default Swaps—once the exclusive domain of Wall Street trading desks—now reach everyday investors through structured notes, ETFs, and mutual funds, often without their knowledge. These complex instruments embed CDS risk inside products marketed as “enhanced yield” or “principal protected” investments, exposing retirement accounts and conservative portfolios to catastrophic losses. Since the 2008 financial crisis, CDS-linked products have generated hundreds of billions in investor losses, triggered landmark enforcement actions, and remain a persistent source of FINRA arbitration claims.

Sigue leyendo

What Are Unrealized Gains and Losses?

Unrealized gains and losses are the changes in an investment’s value while you still own it, measured against what you paid.  The gain or loss exists on paper only, because nothing has been sold, no money has moved, and your brokerage firm recalculates the figure every trading day. If you have been watching an account balance climb for years without ever withdrawing from it, you have been watching unrealized gains.  In this guide, our investment fraud lawyer team will walk you through how unrealized gains and losses work, how to calculate them, and when you pay taxes on them. We also cover how these figures affect your net worth, and when a gain on a statement is a sign that something has gone wrong. Realized and Unrealized Gains: What Changes When You Sell Selling is when a gain or loss becomes realized and may have tax consequences. Until then, your portfolio value and your taxable income are two separate figures that move independently of each other. The two figures serve different purposes when you look at your investments and your taxes. One of them describes how your investments are performing, while the other determines what you owe for the year. The change in value happens continuously, but the tax consequence happens once, on a date you choose by selling. That timing is the one part of the process an investor controls, and it is the reason two people holding the same stock can owe very different amounts. When a Paper Profit Becomes a Realized Gain A realized gain is the difference between what the sale brought in and your adjusted basis in the asset. The IRS calculates a capital gain or loss at the point a capital asset is sold or exchanged, rather than at any point while you hold it. Realized gains are generally taxable in the year the transaction occurs, and they are reported on that year’s return. We want you to understand that a gain becomes taxable when you sell or exchange the asset. That is why a paper profit can exist for years before it becomes a taxable gain. While you still own the investment, the increase in its value is not taxable, but the investment can still generate taxable income.  How Capital Losses Work Once You Sell Sell below your basis, and the paper loss becomes a realized loss that enters the capital losses calculation on your return. Unrealized losses cannot be deducted, because nothing has been disposed of yet. A net capital loss offsets ordinary income only up to an annual limit set by the IRS, and the remainder carries forward into later years. Gains and losses from the same tax year are netted against each other first, so a loss taken in December can reduce a gain taken in March. Your statement can show a gain or loss while you hold the investment, but it does not affect your taxes until you sell. How to Calculate Unrealized Gains and Losses You may calculate an unrealized gain or loss by subtracting what you paid for an investment from its current market value. Multiply the number of shares you own by the current price, then subtract your total cost. The result is your unrealized gain or loss.  Cost basis is the figure to get right, because reinvested dividends, commissions, and stock splits all move it. A gain reported against the wrong basis is more than a clerical problem, because it is a number you may be making decisions on. If you are reading a statement you no longer trust, checking the cost basis is a reasonable place to start. You will find a basis figure on your statement, and you are entitled to ask your brokerage firm how it was calculated. The same subtraction applies to every asset you hold, whatever kind of account holds it. It also applies to shares in mutual funds, where the fund’s daily price replaces the stock price you would use for a single company. Examples of Unrealized Gains and Losses in an Investment Account Three short examples show how the same subtraction works inside an investment account and outside one, and they are as follows: The same arithmetic runs in reverse, because the $12 unrealized gain becomes an unrealized loss the moment the price falls below what you paid. Those amounts can change as the value of the investment changes, but they are not reported as capital gains or losses on your tax return while you still own it. Do You Pay Taxes on Unrealized Gains? You do not pay taxes on an unrealized gain because under current federal rules, a gain is only taxed once you sell.  Unrealized gains do not affect your taxable income until the position is sold, which is why a tax bill can arrive years after the growth did. You do not report unrealized gains to the IRS, and unrealized losses cannot be deducted from your taxes in the year they appear. A tax professional handles the specifics for your situation, because the holding period and the type of account both change the answer. The potential tax implications of a sale are worth understanding before you place the order rather than afterwards. Proposals to tax unrealized gains surface in political debate from time to time, and none of them describes the rules in force today. Capital Gains Taxes and How Long You Held the Asset Capital gains taxes turn on the holding period, and the line the IRS draws is one year. An asset is considered a long-term investment when you hold it for more than a year before selling it. If you sell it within a year of buying it, the gain is short-term. Long-term capital gains are taxed at 0, 15, or 20 percent depending on your taxable income for the year. Long-term capital gains and short-term capital gains are netted within their own class first, which is why a short-term loss does not automatically cancel a long-term gain.  Short-term capital gains...

Sigue leyendo

Fixed Indexed Annuities: How Do They Work & What Are The Risks?

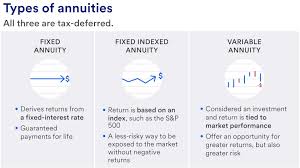
Indexed annuities are among the most aggressively marketed financial products in the United States. In 2024 alone, total indexed annuity sales—combining fixed indexed annuities (FIAs) and registered index-linked annuities (RILAs)—exceeded $192 billion, according to LIMRA. For many retirees, the pitch sounds irresistible: market-linked growth with no downside risk, guaranteed income for life, and an upfront bonus just for signing up. But behind these promises lie complex contractual limitations, punitive surrender charges that can lock up your savings for a decade or more, and a long history of regulatory enforcement actions against the companies and brokers who sell them.

Sigue leyendo

Delaware Statutory Trusts: How They Work, Risks, & Pros And Cons

A Delaware Statutory Trust (DST) is a passive real estate investment vehicle structured as a Regulation D private placement that allows investors to purchase fractional ownership interests in institutional-grade commercial properties. DSTs are most commonly used as replacement properties in IRC Section 1031 tax-deferred exchanges, and they are sold exclusively through registered broker-dealers and financial advisors to accredited investors—primarily retirees who have recently sold rental or investment real estate. If you lost money on a Delaware Statutory Trust due to a broker’s unsuitable recommendation, failure to disclose material risks, or inadequate due diligence on the DST sponsor, you may have a viable claim to recover those losses.

Sigue leyendo

Finra Arbitration: How Does it Work, How Long Does it Take, & More

FINRA arbitration can help investors recover losses, but results depend on preparation and strategy. Our attorneys conduct a detailed case review, draft a fact-rich Statement of Claim, and manage arbitrator selection, discovery, mediation, and hearing presentation. We focus on evidence, deadlines, and damages analysis so clients know what to expect from start to award today.

Sigue leyendo

¿Puede demandar a una empresa de corretaje por pérdidas de inversión?

Investors can sue a brokerage firm to recover losses caused by a broker’s negligence, fraud, or supervisory failures. Because firms are vicariously liable for employees and must enforce compliance policies, liability often rests with the broker-dealer. Some claims target the individual broker for misstatements or illegal conduct. An experienced securities lawyer can evaluate options today.

Sigue leyendo

Solicited vs. Unsolicited Trades: What’s the Difference?

Solicited trades are transactions a broker recommends; unsolicited trades are those an investor proposes. That distinction matters because liability often turns on who initiated the idea when losses occur. Brokers must evaluate suitability under FINRA Rule 2111 and accurately mark order tickets. Reviewing trade confirmations and promptly disputing errors can help protect investors from misconduct.

Sigue leyendo

Stablecoin Risks & Losses

A stablecoin is a type of cryptocurrency designed to maintain a fixed value, usually one U.S. dollar, by holding reserves or using algorithmic mechanisms to offset price movements. Stablecoins are issued by companies like Tether, Circle, Paxos, and PayPal, and are sold through crypto exchanges, yield platforms, and increasingly through financial advisors who recommend them to clients seeking cash alternatives or higher yields. Stablecoins fall into four main categories. Fiat-backed stablecoins like USDT (Tether) and USDC (Circle) claim to hold cash and short-term U.S. Treasuries equal to every token in circulation. Crypto-collateralized stablecoins like DAI require users to lock up crypto assets worth more than the stablecoins they mint. Algorithmic stablecoins like the collapsed TerraUSD relied on code and a paired token rather than reserves. Yield-bearing stablecoins like Ethena USDe and Ondo USDY pay holders interest generated from Treasuries or derivatives strategies. The global stablecoin market reached approximately $318 billion in early 2026, with Tether holding about 60% market share and USDC about 25%. Stablecoin issuers collectively are now the seventh-largest purchasers of U.S. government debt. That growth has coincided with more than $50 billion in investor losses from failed platforms and algorithmic collapses.

Sigue leyendo

Altcoin Investment Losses

Altcoins—any cryptocurrency other than Bitcoin—have moved from the fringes of speculative trading into mainstream brokerage accounts. Solana, Ethereum, XRP, Cardano, and thousands of smaller tokens are now recommended, custodied, or accessed through registered broker-dealers and their crypto affiliates. The combined market capitalization of altcoins exceeded $1.6 trillion at its 2024 peak, only to lose more than 40% of that value during the 2025–2026 drawdown that wiped out memecoins, layer-1 tokens, and DeFi assets alike. For investors who were told altcoins were the "next Bitcoin," appropriate for retirement accounts, or backed by the same regulatory protections as registered securities, those losses are not just unfortunate market outcomes. They may be the result of unsuitable recommendations, inadequate risk disclosures, or outright misconduct by the brokers and advisors who sold them. If you lost money in an altcoin, a tokenized private placement, a crypto IRA, or a broker-recommended altcoin product, you may have legal rights to recover your losses.

Sigue leyendo

Bitcoin Investment Losses

Bitcoin has become a fixture of American investment portfolios. Since the SEC approved the first spot Bitcoin exchange-traded funds in January 2024, broker-dealers and financial advisors have recommended these products to retail investors, retirees, and even conservative clients on fixed incomes. By March 2026, combined spot Bitcoin ETF assets under management reached roughly $86.9 billion, with BlackRock’s iShares Bitcoin Trust (IBIT) alone holding more than $52 billion. Yet in the same window, Bitcoin plunged from an all-time high of $126,296 in October 2025 to around $66,000 by early April 2026—a decline of nearly 50% in six months. For investors who were told Bitcoin ETFs were “safe,” “diversified,” or appropriate for retirement accounts, those losses are not just unfortunate market outcomes. They may be the result of unsuitable recommendations, inadequate risk disclosures, or outright misconduct by the brokers and advisors who sold them. If you lost money in Bitcoin, a Bitcoin ETF, a Bitcoin IRA, or a Bitcoin-related investment scheme, you may have legal rights to recover your losses.

Sigue leyendo
1 2 3 … 8