Junk bonds are corporate bonds rated below investment grade that pay higher yields in exchange for a higher risk of default.
If you invested in high yield bonds and suffered losses you were never warned about, you are not alone. Learning that your broker may not have had your best interests in mind is hard to sit with.
At the Law Offices of Robert Wayne Pearce, P.A., we represent investors harmed by unsuitable investments and undisclosed risks. Our cases involve broker misconduct with junk bonds and other speculative investments.
Junk bonds are not automatically improper investments. The question is whether the broker who recommended them understood your risk tolerance and told you the truth about what you were buying.
What Are Junk Bonds?

Junk bonds are corporate bonds carrying a credit rating below investment grade. The companies behind them have a higher likelihood of failing to repay what they owe. You may also hear junk bonds called high yield bonds or speculative grade debt.
Companies issue these debt instruments when they need to borrow money but cannot earn better credit ratings from the agencies grading corporate creditworthiness. That profile pushes them below the investment grade line.
Junk bonds offer something in exchange for that weakness. To attract investors willing to accept a higher risk of default, they pay higher interest rates than investment grade debt.
Those higher interest payments exist for one reason. There is a real chance you never get your principal amount back at maturity.
How Do Junk Bonds Work?
Junk bonds work the same way most bonds do. You lend money to a company. The company agrees to pay interest on a set schedule and repay debt in full at maturity.
What changes is the credit quality behind that promise. Companies issuing junk bonds carry weaker balance sheets, thinner cash flow, or heavier debt loads than stable companies with investment grade ratings.
Their ability to meet financial obligations is less certain, and credit ratings are the shorthand the market uses for that gap. Lower credit ratings mean a higher risk of default.
The market charges for that risk, and the charge shows up as higher yields. Junk bonds carry coupons above what investment grade bonds pay. None of that extra income is free. Higher yields compensate investors for a higher risk of default, and the junk bond market reprices that risk daily.
How Are Junk Bonds Rated?
Credit rating agencies grade an issuer on how likely it is to make scheduled interest payments and return principal at maturity. The dividing line sits at BBB- from S&P Global Ratings and Fitch Ratings, or Baa3 from Moody’s.
At or above that line is investment grade. Below it is junk.
Eleven credit rating agencies are currently registered with the SEC as nationally recognized statistical rating organizations. Three of these credit agencies dominate corporate bond ratings in the United States:
- Moody’s Investors Service
- S&P Global Ratings
- Fitch Ratings
Below the investment grade line, the scale keeps sorting risk:
- BB and Ba. The least speculative tier. More risk than BBB, less than the categories underneath.
- B. More vulnerable to adverse business, financial, or economic conditions.
- CCC, CC, and C. Vulnerable to nonpayment and dependent on favorable conditions to meet financial commitments. According to S&P Global Ratings, C carries the highest degree of speculation.
- D. The issuer has already failed to pay.
A rating is an opinion about credit risk, not a promise. Rating agencies can raise or lower credit ratings at any point.
What Do Credit Ratings Mean for Investors?
Bonds with better credit ratings trade at higher prices and pay lower yields, because the market sees the issuer as more likely to pay on time. Bonds with lower credit ratings trade at discounted prices and carry higher yields to compensate investors for the added uncertainty.
A change in credit ratings moves the value of your investment fast. Rating agencies review an issuer’s revenue, debt levels, and financial condition continuously. A single downgrade can trigger forced selling by pension funds and other institutional investors restricted to investment grade securities, which pushes bond prices down for everyone holding the same issue.
Junk Bonds vs. Investment Grade Bonds
Both sit inside the fixed income sleeve of a portfolio, which is where the confusion starts. The difference is credit quality.
Investment grade bonds come from stable companies and governments that rating agencies view as highly likely to meet their financial obligations. They pay lower yields because buyers accept less income for a smaller risk of default. Most bonds in a conservative retirement account sit in this asset class.
Junk bonds sit on the other side of the line. They deliver higher yields than their investment grade counterparts, their prices move more sharply, and they carry a higher risk of default that can take your principal with it. Treating the two as interchangeable because both are called bonds is a mistake a broker is paid to prevent.
What Are the Pros of Junk Bonds?
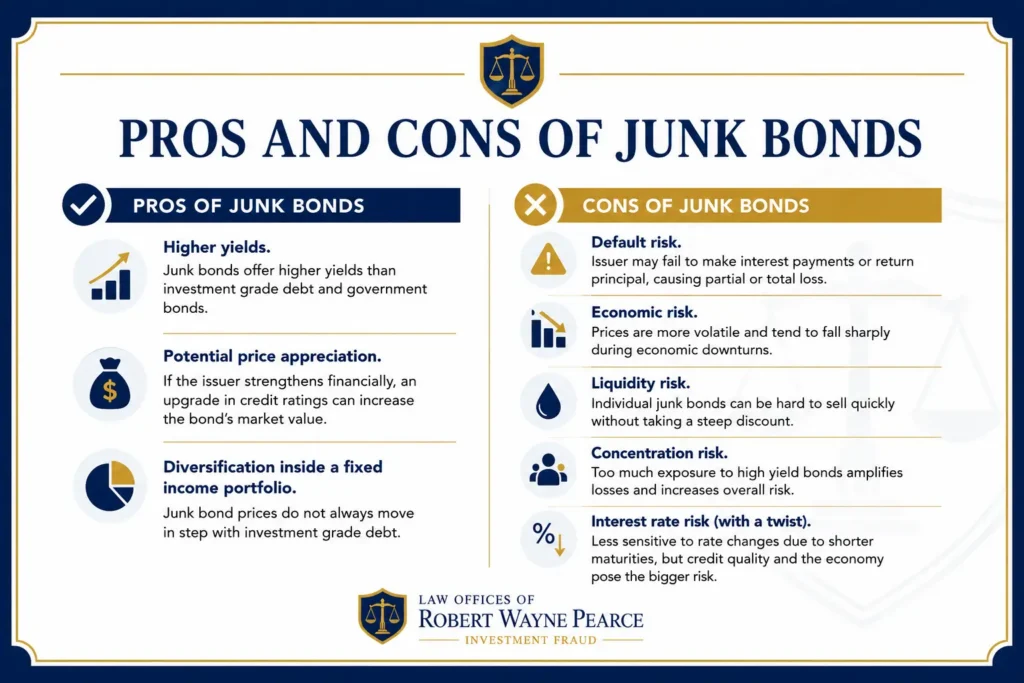
Junk bonds exist because some investors want more income than investment grade debt pays. Three things attract investors to this asset class:
- Higher yields. Junk bonds offer higher yields than investment grade debt and government bonds, which is why a segment of the bond market seeks them out.
- Potential price appreciation. If the issuer strengthens its financial position after you buy, an upgrade in its credit ratings lifts the bond’s market value.
- Diversification inside a fixed income portfolio. Junk bond prices do not always move in step with investment grade debt.
That last point comes with a caution. According to FINRA, high yield bonds tend to move in the same direction as stocks. An investor trying to balance a stock-heavy portfolio may not get the diversification they expect from this corner of the fixed income market.
What Are the Cons of Junk Bonds?
Higher yields always sit on top of higher risk, and one common assumption about junk bonds runs backwards.
- Default risk. When a company fails to make scheduled interest payments or cannot return your principal, you may lose part or all of your investment. Bond defaults are the risk that defines this category.
- Economic risk. Junk bond prices swing far more than investment grade bond prices. In a downturn, investors move toward safer holdings such as Treasuries, and junk bonds fall hard.
- Liquidity risk. Government bonds and highly rated corporate bonds trade in large volumes every day. Individual junk bonds can be hard to sell quickly without accepting a steep discount.
- Concentration risk. A portfolio weighted too heavily toward high yield bonds magnifies every problem on this list. The same danger shows up when a broker stacks bond ladders with junk bonds.
- Interest rate risk, with a twist. Rising interest rates make existing bonds with lower coupons less attractive, which pushes their prices down. According to FINRA, high yield bonds are generally less affected by interest rate moves than other bonds, because they carry shorter maturities and pay higher interest. Interest rates still matter, but the larger danger sits in credit quality and the economy.
A fixed income allocation built on junk bonds is not the conservative sleeve most investors assume it is.
How Do Investors Buy Junk Bonds?
Buying junk bonds directly means purchasing individual junk bonds through a brokerage account. According to FINRA, par value is typically $1,000 per bond. Most corporate bonds require a minimum investment of that amount.
Many junk bond investors reach the high yield market through mutual funds and exchange traded funds instead. These funds hold portfolios spanning dozens or hundreds of issuers, which limits the damage any single default can do. Mutual funds also give smaller investors exposure they could not build alone.
The choice between buying junk bonds directly and investing in junk bonds through a fund comes down to your experience, your research access, and your tolerance for concentration risk. Either path puts you in speculative grade securities. If you are a risk averse investor, or you depend on your portfolio for income, understand the potential for loss before money goes into the junk bond market.
What Moves Junk Bond Prices?
Three forces drive junk bond prices. The first is the credit picture of the issuer, which is where default risk lives. Anything that changes the issuer’s ability to pay moves the price of its bonds.
The second is the economy. Economic uncertainty pushes investors out of high yield bonds and into safer assets, and junk bonds fall, while improving economic conditions do the reverse. Demand for the bond increases and prices recover.
The third is investor sentiment. The high yield market tracks the stock market more closely than most bonds do, so an equity selloff often drags junk bond prices down with it. That correlation matters if a broker said these bonds would balance your equity risk. Interest rates matter less here, which is why a portfolio positioned for rising interest rates can still lose value when credit conditions turn.
What Are Fallen Angel Bonds?
Fallen angels are bonds issued with investment grade ratings that were later downgraded to junk status. The downgrade follows a deterioration in the issuer’s financial condition. Declining revenues, rising debt levels, or economic pressure on the issuer’s ability to pay will push credit ratings down.
Once a bond crosses below the investment grade line, pension funds and institutional investors bound to hold only bonds with better credit ratings have to sell. Watching a bond you bought as safe drop sharply on forced selling is disorienting.
Some investors target fallen angels for that reason. They treat them as higher quality than bonds issued with junk status from the start, and they may climb back into investment grade territory if the company recovers.
When Are Junk Bonds Unsuitable Investments?
Two standards govern what a broker can recommend to you.
FINRA Rule 2111, the suitability rule, requires a firm or associated person to have a reasonable basis to believe a recommended transaction or strategy suits the customer. According to FINRA, the customer’s investment profile covers:
- Age.
- Other investments.
- Financial situation and needs.
- Tax status.
- Investment objectives.
- Investment experience.
- Investment time horizon.
- Liquidity needs.
- Risk tolerance.
Regulation Best Interest goes further. Broker-dealers have had to follow this SEC rule since June 30, 2020. It requires them to act in your best interest when recommending a securities transaction or strategy, without putting their own financial interests ahead of yours. Firms satisfy it through four component obligations. Two cover disclosure and care. The other two cover conflicts of interest and compliance.
A junk bond recommendation that ignores these factors may be unsuitable, whether the broker recommended individual bonds or a high yield fund. Investing in junk bonds fits an investor with a higher risk tolerance and money they can afford to lose. Conservative investors, retirees on fixed income, and anyone who cannot absorb a significant risk to principal are generally poor candidates.
Overconcentration is a frequent problem. A broker puts too large a share of your portfolio into high yield bonds. That lack of diversification exposes you to more risk of default than your profile supports.
FINRA has acted on this exact failure. According to FINRA, RBC Capital Markets did not maintain a reasonably designed supervisory system for recommendations of high yield bonds from July 2013 through June 2016. The firm failed to review more than 100 conservative customer accounts for potentially unsuitable concentrations.
RBC was censured, fined $550,000, and ordered to pay $456,155 in restitution plus interest.
Your broker has a duty to explain these risks to you directly. In our view, handing you a prospectus full of boilerplate risk language does not discharge that duty.
What to Do If You Lost Money in Junk Bonds
Losing money on junk bonds does not automatically mean your broker did something wrong. Bond prices fluctuate, and junk bond defaults are a known risk in high yield investing.
What matters is the cause. Did normal market conditions produce your losses, or did broker misconduct? Misconduct usually looks like a recommendation that never fit your financial profile, a failure to disclose the increased risk, or too much of your portfolio pushed into junk bonds.
If misconduct played a role, you may have claims worth pursuing:
- Unsuitability.
- Breach of fiduciary duty.
- Overconcentration and failure to diversify.
- Omission of material facts that would have changed your decision to invest.
Most retail investors pursue these claims through FINRA arbitration. According to the SEC, most account agreements with broker-dealers contain arbitration clauses requiring customers to arbitrate disputes instead of suing in court, and arbitration can be cheaper and quicker than litigation. An experienced stockbroker fraud lawyer can review your investment and tell you whether filing makes sense.
Contact an Investment Fraud Lawyer to See if You Have a Case
You do not have to absorb losses caused by someone else’s misconduct. Our firm has represented investors nationwide for more than 45 years on a contingency fee basis. You pay nothing unless we recover money for you.
Contact the Law Offices of Robert Wayne Pearce, P.A. today for a free consultation. Speak with an investment fraud lawyer about what actually happened in your account. If a broker or firm in our home state handled your money, our Florida investment fraud lawyer team can review your case now.